Home Equity Line Of Credit Rates Pnc Bank

Ever found yourself daydreaming about that dream kitchen reno, or that epic vacation you've been putting off? Well, friend, let me introduce you to a little something called a...

Ever found yourself daydreaming about that dream kitchen reno, or that epic vacation you've been putting off? Well, friend, let me introduce you to a little something called a Home Equity Line of Credit (HELOC). Now, I know what you're thinking, "That sounds fancy, and kinda scary." But stick around, 'cause I'm about to make it sound as exciting as a weekend getaway to your favorite beach spot.
So, what's a HELOC, anyway?
Imagine you've got a house, and over time, it's gained some value. A HELOC is like a special credit card that uses that increased value as collateral. It's a line of credit, which means you can borrow money as you need it, up to a certain limit. And here's the kicker - you only pay interest on what you actually borrow.
PNC Bank's got the scoop on HELOCs
Now, you might be wondering, "Why should I care about PNC Bank?" Well, let me tell you, they're kinda like the cool kid on the block when it comes to HELOCs. They've got some pretty sweet rates, and they're always updating their offers to keep up with the times.
Must Read
But here's the thing - rates can change faster than the weather in April. So, it's always a good idea to check their website or give them a call to see what they've got going on right now. You might just find a rate that'll make your eyes widen like a kid on Christmas morning.
Why should you care about HELOC rates?
Alright, so you've got a HELOC, but why should you care about the rates? Well, let me put it this way - rates are like the gas in your car. The lower the rate, the further you can go without breaking the bank. With a lower rate, you'll pay less in interest, which means more money in your pocket for the things you actually want - like that fancy espresso machine you've been drooling over.
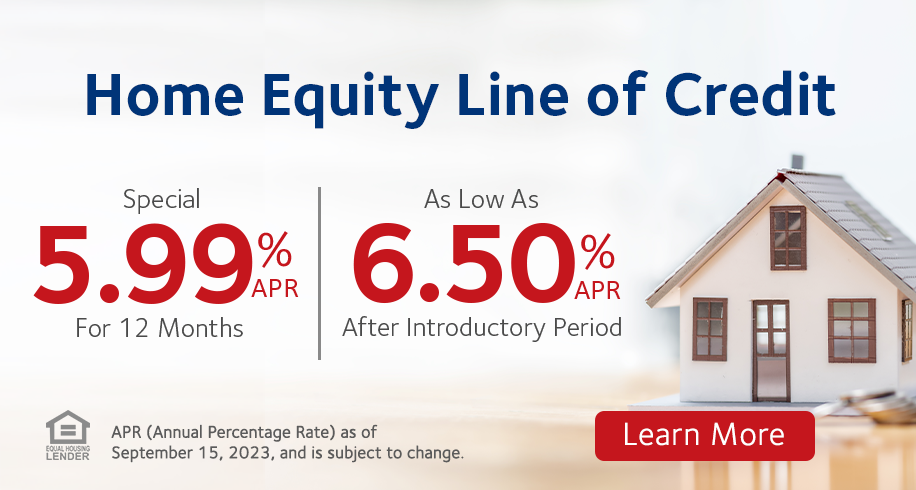 Home Equity Rates › 1st United Credit Union
Variable vs. Fixed: The great rate debate
Now, you might be thinking, "Okay, I get it. Lower rates are better. But what kind of rate should I go for?" Well, my friend, that's a question as old as time itself. Or at least, as old as HELOCs. The answer? It depends.
Variable rates can go up and down like a rollercoaster, but they usually start off lower than fixed rates. Fixed rates, on the other hand, stay the same no matter what the economy does. It's like choosing between a thrilling rollercoaster ride or a calm, steady carousel. Both have their pros and cons, so it's up to you to decide which one suits your style.
But wait, there's more!
Besides the rates, PNC Bank's HELOCs come with some pretty sweet perks. Like, did you know you can use your HELOC to consolidate debt? That's right - you can turn all those pesky credit card bills into one manageable payment. It's like turning a chaotic game of Tetris into a neat, organized line of blocks.
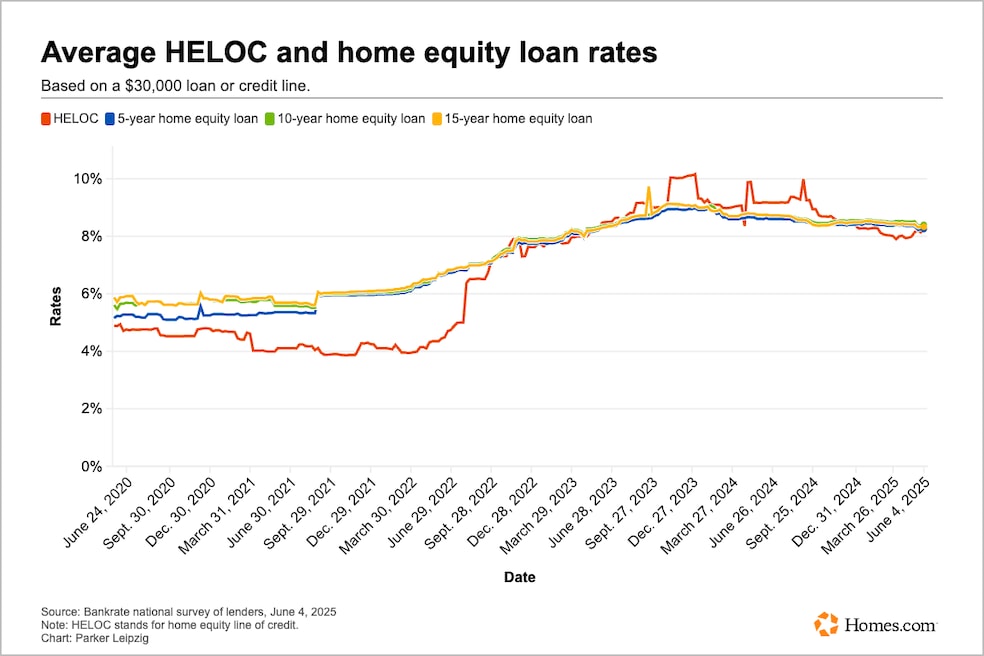 Chart of the day: Rates on home equity loans and lines of credit rise
And get this - PNC Bank offers a 12-month introductory period with no annual fee. That's like getting a whole year of free passes to your favorite amusement park. Who wouldn't want that?
So, should you get a HELOC?
Well, that depends on you, buddy. Are you looking to renovate your home, consolidate debt, or fund a big project? If so, a HELOC might be just the ticket. But remember, it's like driving a car - you've got to be responsible and pay it back. After all, nobody wants to end up in a financial ditch.
So, what do you say? Ready to explore the world of HELOCs and see if it's the right fit for you? Just remember to do your research, compare offers, and always read the fine print. And who knows? You might just find yourself on the fast track to your dream project.
