Why Is Affirm Showing On My Credit Report

So, there I was, minding my own business, checking my credit report like the responsible adult I am (well, trying to be), when I stumbled upon something that made me do a doub...
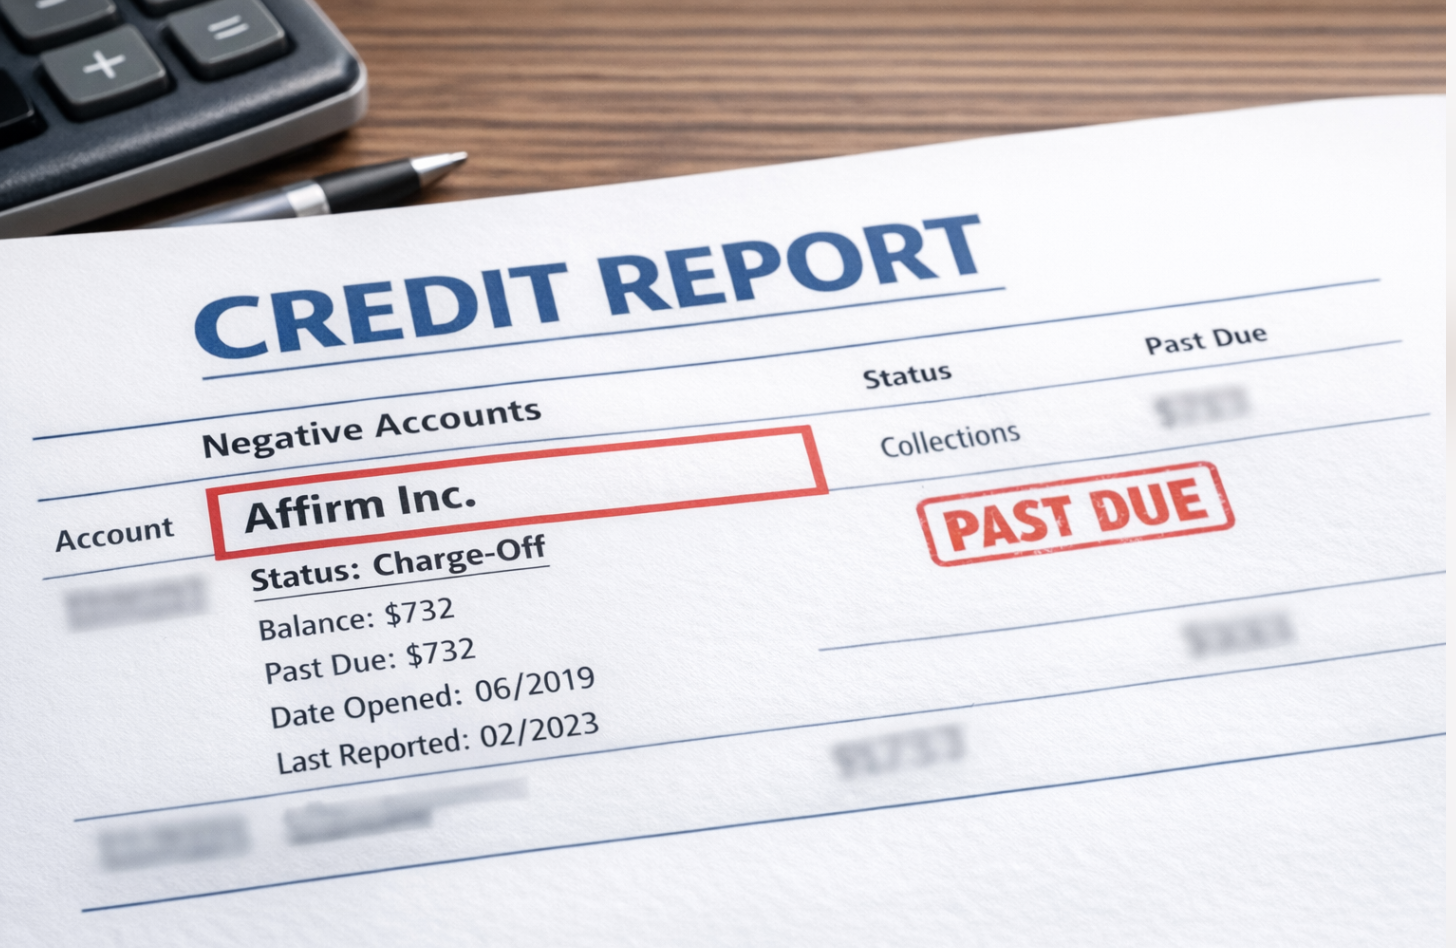
So, there I was, minding my own business, checking my credit report like the responsible adult I am (well, trying to be), when I stumbled upon something that made me do a double-take. Right there, in black and white, was an entry I didn't recognize: "Affirm". Now, I'm all for a good mystery, but this was one I wasn't expecting. I mean, who is this Affirm character, and why are they crashing my credit party?
First things first, let's get one thing straight. This isn't some secret admirer or long-lost relative. No, no, no. Affirm is a buy now, pay later service, and it's been making waves in the retail world. You might have seen it at checkout when you're shopping online - you know, that option that lets you split your purchase into four equal payments, interest-free. Sounds too good to be true, right? Well, it's not, but there's a catch.
Here's where things get a bit tricky. See, when you use Affirm, they report your activity to the credit bureaus. Now, don't go thinking they're doing this out of the goodness of their hearts. No, they're doing it because it's good for business. You might be wondering why, and that's a great question. The answer is simple: credit building.
Must Read
Why on Earth Would They Do That?
Alright, let me explain. Affirm wants you to build credit, because the better your credit, the more likely you are to use their service. It's a win-win, really. They get more customers, and you get to build your credit history without having to take out a loan or open a credit card. It's like a little credit-building hack, if you will.
 Affirm Inc on Your Credit Report? How to Handle Charge-Offs | ASAP
But here's the thing, Affirm isn't just reporting your on-time payments. No, they're also reporting your missed payments. So, if you're late with a payment (or heaven forbid, miss one altogether), it's going to show up on your credit report. And that, my friend, can hurt your credit score.
So, Should You Use Affirm?
That's a question only you can answer. If you're responsible with your money, make your payments on time, and want to build credit without taking on more debt, then Affirm might be a good option for you. But if you're not great with money, or you're already struggling with debt, then it might be best to steer clear.
 Affirm Charge-Off Showing Twice on Credit Report: How to Fix It Fast
Remember, the key to using services like Affirm is responsibility. It's all about using credit wisely and making your payments on time. If you can do that, then Affirm can be a useful tool for building credit. But if you can't, then it might just end up hurting your credit score.
So, there you have it. That's why Affirm is showing up on your credit report. It's not a mysterious stranger, but a service that's trying to help you build credit (while also helping themselves, of course). Use it wisely, and it can be a helpful tool. But misuse it, and it can cause more harm than good. The choice is yours.
